Devdatt Nerurkar
Founder of WiserWill
Estate Inventory Guide: What to List Before Your Will
A missing account, an unlisted life insurance policy, or a folder no one can find can create more work for your family than a complicated Will ever will. This estate inventory guide helps you gather the information behind your plan, so the people you trust can locate assets, understand obligations, and carry out your wishes with fewer unanswered questions.
An estate inventory is not a public document and it is not a substitute for a Will. Think of it as a practical private record that supports your Will. Your Will says who should receive eligible assets. Your inventory explains what you own, where it is held, what you owe, and who may need to be contacted.
Start With the Information Your Family Cannot Easily Find
Begin with your legal name, date of birth, current address, and any former names used on financial or property records. Add the location of your original signed Will, along with the names and contact details of your executor, alternate executor, attorney, accountant, financial adviser, and insurance agent, if applicable.
Do not put passwords, PINs, Social Security numbers, or full account numbers directly in a document that may be printed or shared. Instead, record where secure access instructions are stored. This might be a password manager, a locked home file, or a secure digital vault. Your executor needs a reliable path to information, not unrestricted access before it is necessary.
It also helps to note people who should be notified. This can include close family members, a business partner, a landlord, an employer, or the person caring for a pet. The goal is not to turn your inventory into a personal diary. It is to leave clear, useful direction when your family may be under pressure.
Build Your Estate Inventory by Asset Type
Work through one category at a time. You do not need exact values for every item on day one. A reasonable estimate, the account location, and the last four digits of an account number are often enough to begin. Update values later when you can.
Real Estate and Personal Property
List every home, land parcel, rental property, timeshare, or other real estate interest. Include the property address, how title is held, the mortgage lender, and where the deed and related documents are kept. If you co-own property, record the co-owner’s name and whether you believe the property has survivorship rights. Ownership structure can affect whether an asset passes under a Will, so confirm the details when needed.
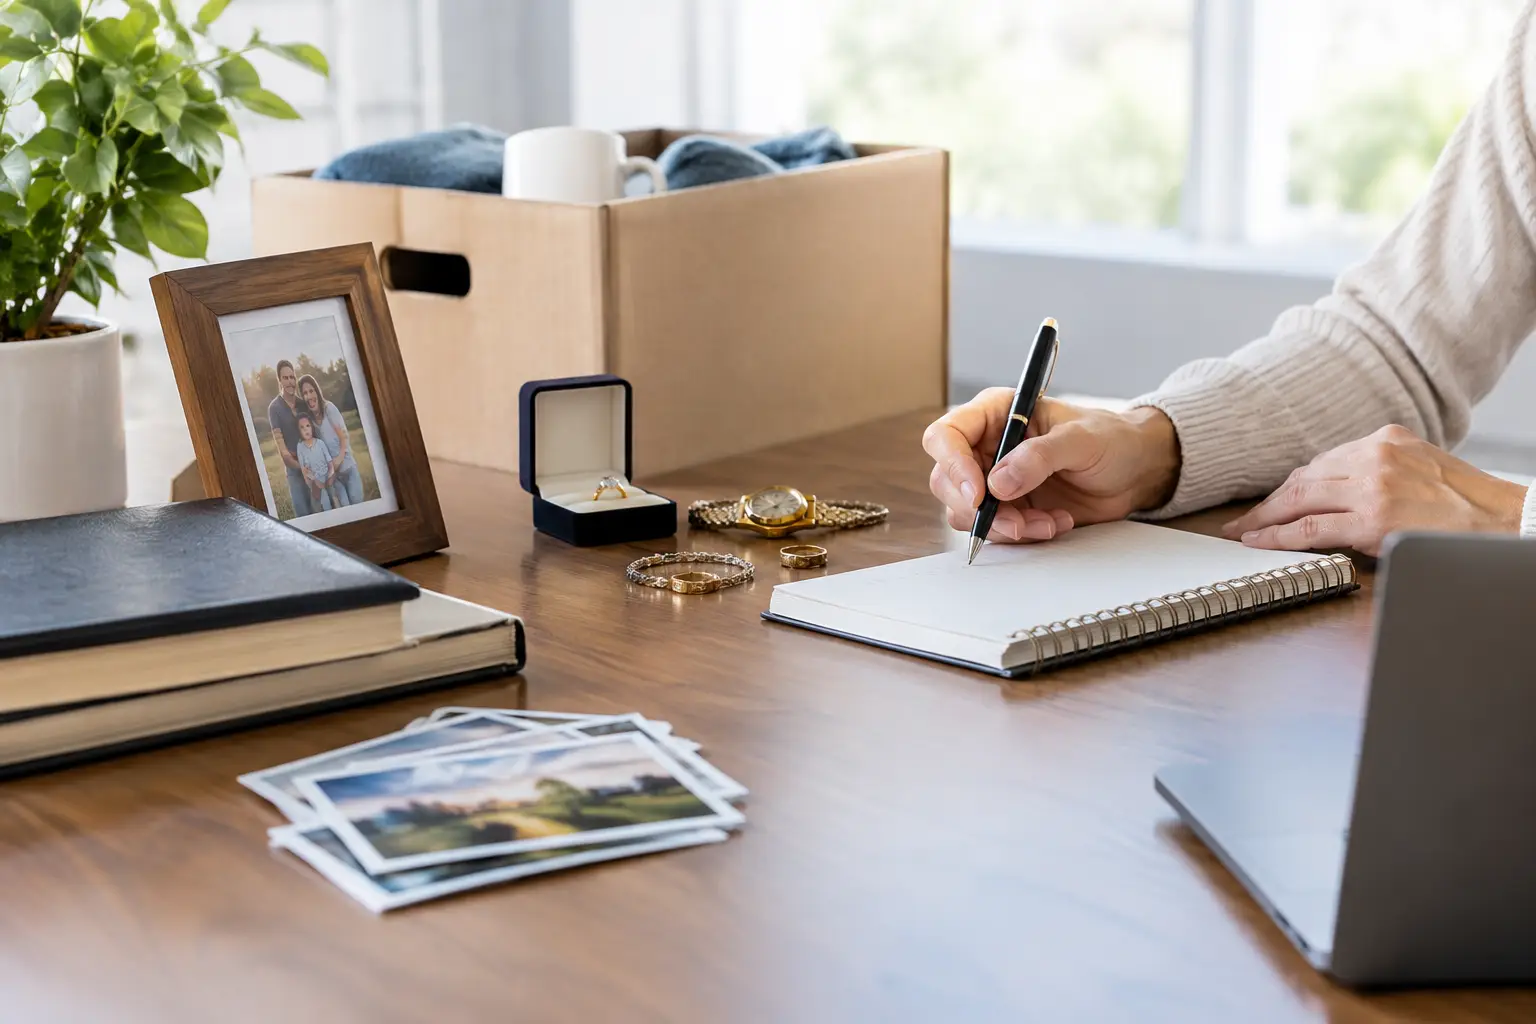
Then record significant personal property. This may include vehicles, jewelry, art, collectibles, firearms, family heirlooms, furniture, and valuable electronics. For items with strong sentimental value, add a brief description and photograph. A value is useful, but a clear description can prevent a surprising amount of conflict.
If you want certain belongings to go to specific people, make sure those wishes are reflected in your legally valid estate-planning documents where required. An inventory can remind your executor of your intent, but it may not control distribution on its own.
Financial Accounts and Investments
Include checking and savings accounts, certificates of deposit, brokerage accounts, retirement plans, stock options, cryptocurrency holdings, and digital payment balances. Record the institution, account type, approximate balance, and the location of recent statements.
For retirement accounts and life insurance, identify the named beneficiaries and the date you last reviewed those designations. These assets often pass directly to the beneficiary named on the account or policy, rather than through a Will. That can be helpful, but it also means an outdated beneficiary form may defeat your current intentions.
Business owners should list company interests, partnership agreements, buy-sell agreements, key contracts, and the location of accounting records. A business is not just another asset. It may require immediate operational decisions, and your executor may need professional support to protect its value.
Insurance, Benefits, and Money Owed to You
Record life, health, disability, long-term care, homeowners, auto, and umbrella insurance policies. Include the insurer, policy number reference, agent contact, coverage type, and beneficiary details where relevant.
Also note employment benefits, pensions, unpaid bonuses, deferred compensation, and any money owed to you through loans, legal claims, or business receivables. A family cannot claim benefits they do not know exist. Even a short entry can help them ask the right questions.
Digital Assets and Online Life
Digital assets deserve their own section. List email accounts, cloud storage, websites, domain names, online businesses, social media accounts, digital photos, subscription services, and cryptocurrency wallets. State what you want done with them, where appropriate.
Be practical about access. Many online services have their own rules for accounts after death, and some prohibit sharing login credentials. Your inventory should identify the service and the location of lawful access instructions, rather than exposing passwords in the document itself.
Do Not Forget Debts and Ongoing Bills
An accurate inventory is not only about what you own. Your executor also needs to understand what you owe. List mortgages, auto loans, credit cards, personal loans, student loans, tax obligations, business debts, and recurring household bills.
Include the creditor, approximate balance, payment due date, whether payments are automatic, and where statements are stored. This does not mean every debt must be paid from every asset. The treatment of debts depends on applicable law, the estate’s resources, ownership arrangements, and beneficiary designations. Still, a clear list prevents missed payments and helps your executor get organized quickly.
Match the Inventory to Your Will
Once your inventory is complete, compare it with your Will. Ask whether every major asset has a clear path. If an account has a payable-on-death beneficiary, does that designation still match your current plan? If you have acquired a home, started a business, remarried, divorced, or welcomed a child, does your Will still reflect your life?
This review is also a good time to consider who can realistically serve as executor. The right person is usually organized, trustworthy, and willing to handle paperwork, communication, and deadlines. They do not need to know every detail today, but they should know that an inventory exists and how to find it when the time comes.
If you have minor children, review guardian nominations separately. A financial inventory cannot make parenting decisions, but it can help a chosen guardian understand insurance coverage, education savings, recurring expenses, and the resources available for the child’s care.
Store It Privately and Update It Regularly
Keep your estate inventory separate from your signed Will, but store both where they can be found. Give your executor clear instructions about the location without circulating sensitive records widely. A secure physical file and a protected digital copy can be sensible, depending on your circumstances.
Review the inventory at least once a year and after a major change, such as buying or selling property, opening a new account, changing jobs, marrying, divorcing, having a child, or receiving an inheritance. Cross out old entries rather than leaving uncertainty, and date each update.
Estate planning does not have to begin with legal jargon or a stack of documents. Begin with a clear record of your life as it exists now. When you are ready to create or revise your Will, that simple act of organization can give your family something deeply valuable: direction when they need it most.
