Devdatt Nerurkar
Founder of WiserWill
CPF Nomination Versus Will: What Goes Where
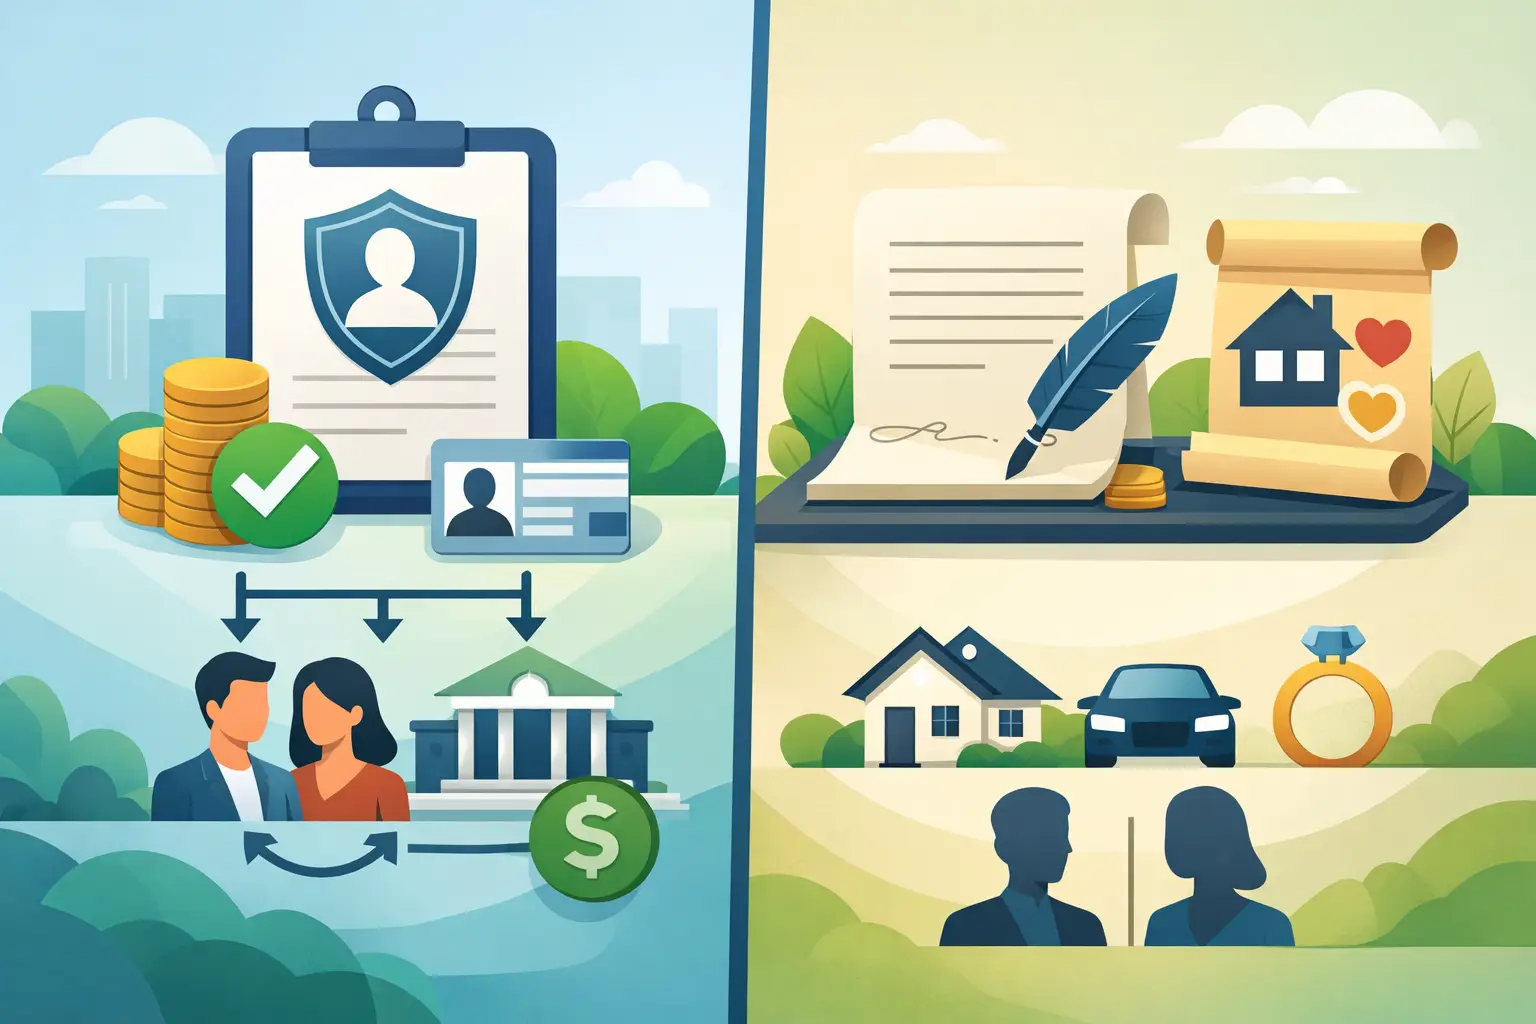
A CPF nomination versus will is not a choice between two documents that do the same job. In Singapore, they deal with different assets. Your CPF nomination directs your CPF savings to the people you name, while your Will sets out what should happen to assets in your estate, such as your home, bank accounts, investments, and personal belongings.
Mixing them up can create avoidable stress for the people you leave behind. A carefully written Will cannot override a valid CPF nomination. Equally, a CPF nomination does not tell your family who should receive the rest of your assets or who should care for young children.
The practical answer for many people is simple: make sure both are in place and that they reflect the same overall intentions.
CPF Nomination Versus Will: The Key Difference
CPF savings do not form part of your estate when you die. This means they are not distributed under your Will, even if your Will specifically mentions your CPF account. Instead, CPF savings are paid to the nominees named in your valid CPF nomination.
A Will covers assets that form part of your estate. These may include money in your personal bank accounts, shares and investments held in your own name, a car, jewelry, and your share of a property. Your Will also allows you to appoint executors to manage your estate and guardians to care for minor children.
Think of a CPF nomination as a direct instruction for one important category of savings. A Will is your wider plan for the assets and responsibilities that remain.
What a CPF nomination does
With a CPF nomination, you name one or more people to receive your CPF savings after your death. You can decide how those savings should be divided among them. The payment is handled separately from the administration of your estate, which can help your nominees receive the funds without waiting for the entire estate to be settled.
This can matter greatly where family members need money quickly for daily expenses, housing payments, or other immediate needs. It can also provide clarity where your preferred CPF beneficiaries are different from the people inheriting your other assets.
If you do not make a CPF nomination, your CPF savings are generally distributed according to Singapore's intestacy rules through the Public Trustee. Your Will does not step in to control that distribution.
What a Will does
A Will gives you control over the assets that do fall into your estate. You can state who receives specific items, divide the rest of your estate in percentages, and name substitute beneficiaries in case someone dies before you.
It also lets you appoint an executor. This is the person you trust to apply for the necessary legal authority, collect estate assets, pay debts, and distribute what remains according to your instructions. For parents, a Will is also the place to name guardians for children under 21.
Without a valid Will, estate assets are distributed under intestacy rules. That may produce an outcome you would not have chosen, especially for unmarried partners, stepchildren, close friends, or charitable causes. It can also make the estate administration process more time-consuming for those left behind.
Why You Usually Need Both
Consider a married parent with CPF savings, a savings account, insurance proceeds, a share in a home, and two young children. A CPF nomination can direct CPF savings to a spouse, children, or another trusted person. But it cannot appoint a guardian for the children, give a specific item to a sibling, or explain how the non-CPF assets should be divided.
On the other hand, a Will can appoint guardians and distribute the estate, but it cannot redirect CPF savings away from the nominees in a valid CPF nomination. Relying on only one document leaves part of the picture unaddressed.
Using both documents does not mean every asset must go to the same people in the same proportions. Your choices may differ for good reasons. For example, you may want CPF savings to support a spouse immediately, while your Will provides that a larger share of other assets is held for your children's future needs.
The key is to make those choices deliberately. Your family should not have to guess whether a difference was intentional or an oversight.
Common Situations That Need a Review
Estate planning is not a one-time task. Your CPF nomination and Will should be reviewed after significant life changes, particularly when the people you want to protect or the assets you own have changed.
Marriage deserves special attention. Under CPF rules, a marriage revokes an existing CPF nomination. That can leave you without a valid nomination unless you make a new one after getting married. Divorce does not automatically revoke a CPF nomination, so it is equally important to review your named nominees and intended shares after a divorce.
You should also check both documents after the birth or adoption of a child, the death of a nominee or beneficiary, buying a property, receiving a major inheritance, or starting a business. A nomination made when you were single may no longer make sense once you have a spouse and children. A Will written before you acquired assets may need clearer distribution instructions.
If you have children who are still minors, do not stop at naming them as beneficiaries. Consider who should manage assets for them and who you would want to care for them if both parents are unable to do so. These are decisions a Will can help you record clearly.
How to Keep Your Instructions Clear
Start by listing your assets in two groups: CPF savings and estate assets. This small exercise makes it easier to see why a CPF nomination and a Will work together rather than compete.
Next, consider the people who depend on you. Who would need immediate financial support? Who should receive long-term assets? Who would be able to handle the practical work of administering your estate? Your answers may point to different roles for a CPF nominee, a Will beneficiary, an executor, and a guardian.
Then check the names and details you use. Use the correct legal names for nominees and beneficiaries, and make sure the percentage shares you choose add up as intended. If you name more than one person, think through what should happen if one of them dies before you or is unable to receive the gift.
Finally, tell your executor or a trusted family member where to find your Will. You do not need to share every detail of your estate plan, but someone should know that a Will exists and how to locate the signed original when it is needed.
A Simple Checklist Before You Finalize
Before you treat your estate plan as complete, check these four points:
- You have a valid CPF nomination that reflects your current wishes.
- Your Will covers your non-CPF assets and names an executor.
- You have appointed guardians if you have children under 21.
- You review both documents after marriage, divorce, a new child, or major changes to your assets.
For more complex circumstances, such as overseas assets, a family business, or concerns about a beneficiary's ability to manage money, professional legal advice may be appropriate. The goal is not to make your plan complicated. It is to make sure it works when your family needs it.
A clear CPF nomination can help your CPF savings reach the right people directly. A clear Will can protect everything else that matters, including the people who will carry out your wishes. Taking time to put both in place is one of the most practical ways to give your family direction when they may need it most.
